A Lifetime of Savings Meets an Unexpected Obstacle
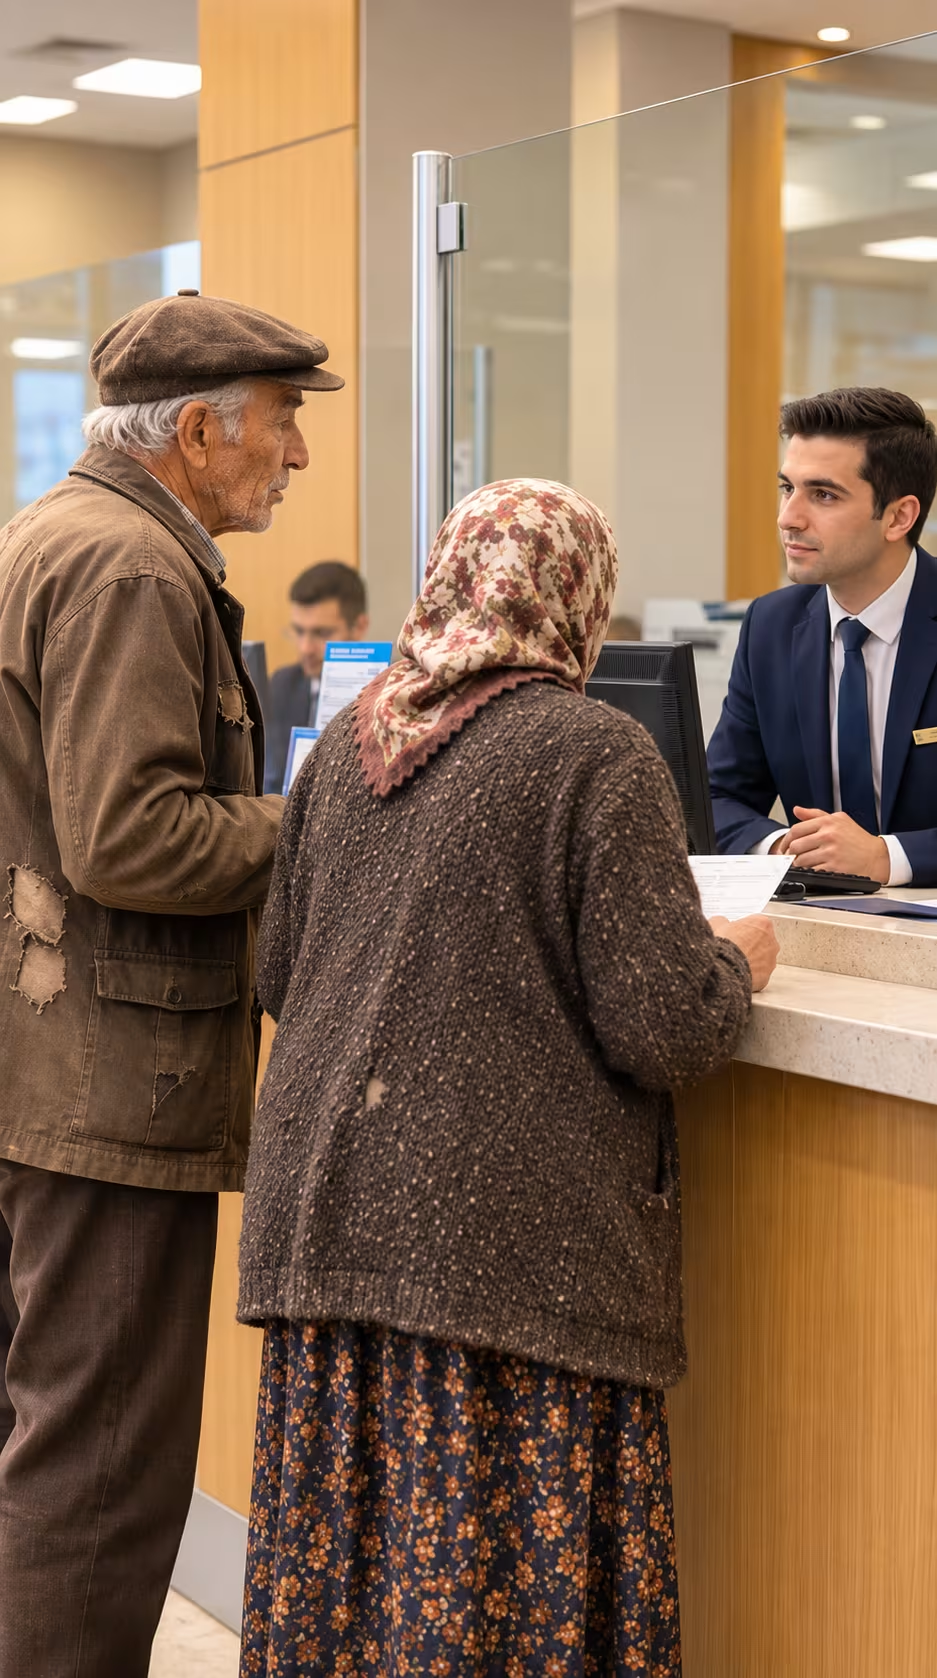
The elderly man carefully placed a worn leather envelope on the bank counter.
Inside were thousands of dollars that he and his wife had saved over many years.
Seventy-eight-year-old Robert Miller stood beside his wife, Margaret, waiting for the employee to count the money.
But the young bank employee barely glanced at the envelope before shaking his head.
“I’m sorry, sir. I can’t approve this deposit.”
Robert looked confused.
“We’ve been customers here for thirty-two years.”
The employee, Jason Parker, pushed the envelope back across the counter.
“These funds require additional verification, and I can’t accept them today.”
Margaret gently touched her husband’s arm.
They had come to deposit their savings before making an important decision about their future.
Neither expected the visit to become a confrontation.
A Request That Should Have Been Simple
Robert opened the envelope and showed Jason the neatly arranged bills.
The couple wanted to deposit $18,400 into their existing joint savings account.
They had accumulated the money through years of careful budgeting and occasional cash withdrawals.
Robert had recently decided that keeping so much money at home was unnecessary.
Their granddaughter had encouraged them to place it in a bank.
Jason examined the account information on his computer.
He noticed that the couple rarely deposited large amounts of cash.
Their usual transactions involved pension payments, utility bills, and modest withdrawals.
“This is much larger than your normal deposits,” he explained.
Robert nodded.
“That’s because we’ve been putting money aside for years.”
Jason asked several questions about the source of the funds.
Margaret answered patiently, explaining their pensions and Robert’s former carpentry business.
But Jason remained uncomfortable.
He believed the unusual amount required approval from someone with greater authority.
Instead of requesting that review, he told the couple to return another day.
Robert looked at the envelope, disappointed that their explanation had apparently changed nothing.
The Documents Margaret Had Carefully Prepared
Margaret opened her handbag and removed a small folder containing financial records.
She had brought pension statements, older withdrawal receipts, and identification documents.
Their granddaughter had suggested carrying the paperwork in case questions arose.
Jason examined several pages but seemed uncertain how to proceed.
Some receipts were years old, and not every dollar could be traced individually.
Margaret explained that they had also saved small amounts from household expenses.
“We weren’t trying to hide anything,” she said.
“We simply wanted to keep money available for emergencies.”
Jason replied that he wasn’t accusing them of wrongdoing.
However, he repeated that the transaction couldn’t proceed.
A woman waiting nearby overheard the conversation and approached the customer service desk.
She quietly asked whether a supervisor could assist the elderly couple.
The receptionist contacted bank manager Elizabeth Morgan, who was reviewing paperwork in her office.
Elizabeth had managed the branch for eleven years.
When she heard that longtime customers were being turned away, she came to investigate.
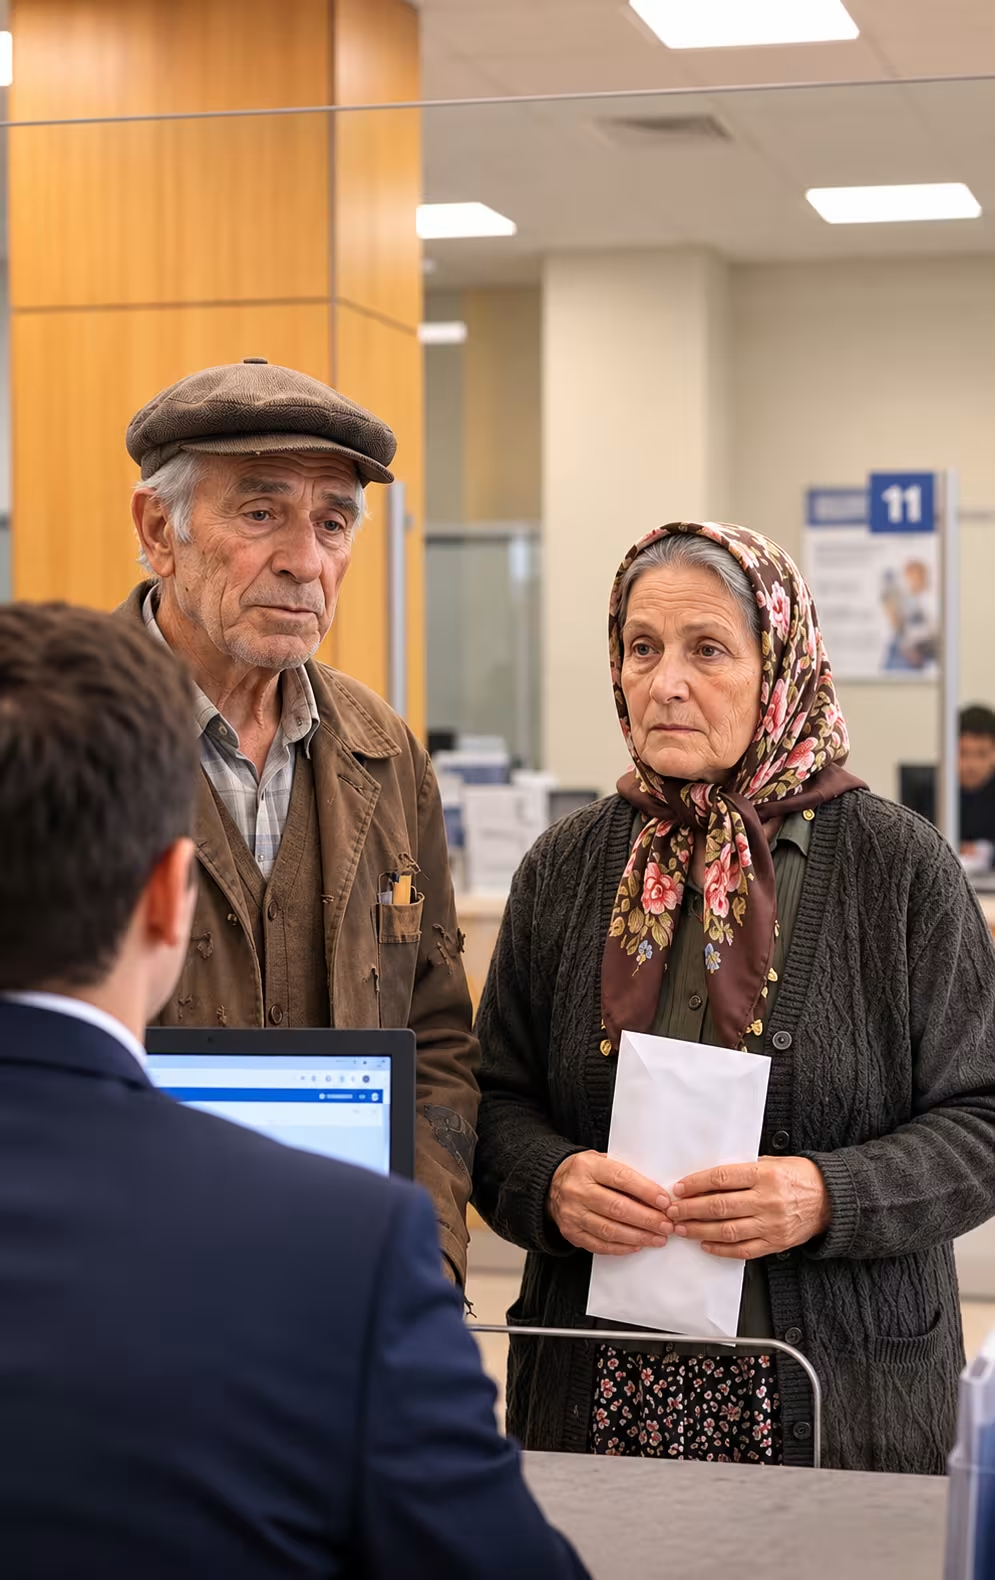
She found Robert standing silently beside Margaret, holding the envelope against his chest.
The Manager Asks a Different Question
Elizabeth introduced herself and invited the couple to a private consultation desk.
She asked Jason to join them and explain the situation.
Jason described the unusually large cash deposit and his concerns about verification.
Elizabeth listened without interrupting.
Then she asked a question that changed the conversation.
“Did our system actually require you to reject the transaction?”
Jason hesitated before answering.
“No. It flagged the amount for additional review.”
Elizabeth examined the notification on his screen.
The alert required documentation and an authorized employee’s review before processing.
It did not automatically prohibit the deposit.
Elizabeth explained that banks must follow procedures for identifying customers and reviewing certain transactions.
But she also emphasized that employees should distinguish between a required review and an outright refusal.
Robert quietly asked whether they had done something wrong.
Elizabeth reassured him that an unusual deposit did not automatically mean misconduct.
She reviewed their identification and asked additional questions about the savings.
Margaret provided the documents she had brought.
Elizabeth then contacted the bank’s internal compliance team for guidance.
The couple waited while the necessary checks were completed.
The money remained on the desk, still inside Robert’s worn envelope.
The Manager Orders the Deposit Approved
After reviewing the information, the compliance representative confirmed that the deposit could proceed.
The required documentation had been completed, and no unresolved restriction prevented acceptance.
Elizabeth returned to the consultation desk with the decision.
“Mr. and Mrs. Miller, we can accept your deposit today.”
Margaret exhaled with relief.
Robert looked toward the envelope he had carried so carefully.
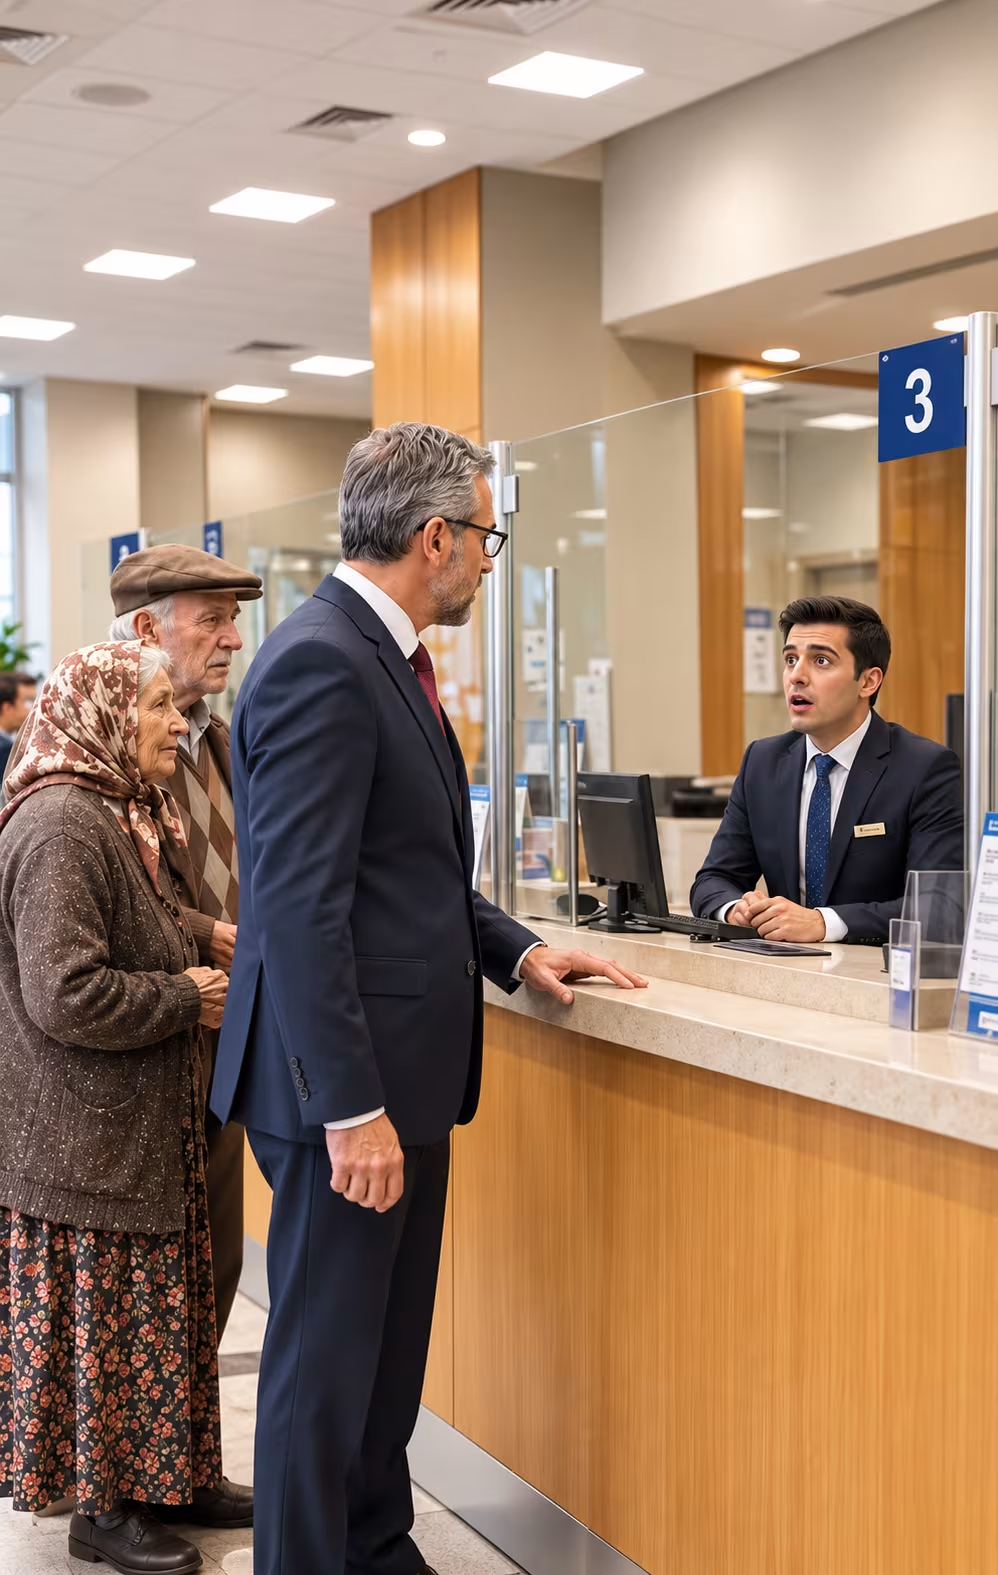
Elizabeth turned to Jason.
“The review is complete. Approve their deposit request and process it according to procedure.”
Jason nodded and reopened the transaction.
He verified the account details and began counting the cash using the bank’s counting equipment.
Robert watched each bundle pass through the machine.
The total matched the amount they had reported: $18,400.
Jason completed the deposit and printed a confirmation receipt.
He handed it to Margaret, who examined the account number and transaction amount.
Everything was correct.
“I’m sorry I turned you away before requesting the proper review,” Jason said.
Robert accepted the apology.
“We just wanted to make sure our savings were somewhere safe.”
Elizabeth explained that the bank would retain the necessary transaction records.
She also reminded the couple that they could request assistance whenever a banking procedure seemed confusing.
For the first time since entering the branch, Margaret smiled.
Why the Savings Meant So Much
With the deposit completed, Elizabeth asked whether the couple needed additional assistance.
Margaret explained that the money represented more than ordinary household savings.
Robert had spent forty years working as a carpenter before retiring.
Margaret had worked part-time at a public library while raising their children.
Neither had earned a particularly large income.
They had saved gradually, sometimes placing only twenty dollars into their household envelope.
Their original plan was to keep the money available for unexpected expenses.
But recent conversations with their family had changed their priorities.
They wanted to use part of the savings to make their home safer as they grew older.
Robert had begun struggling with the steep steps leading to their front door.
They hoped to install a safer entrance and improve the bathroom.
Elizabeth suggested speaking with a qualified financial adviser about maintaining an emergency reserve.
She made clear that the deposit itself did not require purchasing any additional banking products.
Margaret appreciated that distinction.
The couple left the branch with their receipt carefully tucked inside the same leather envelope.
This time, the envelope contained no cash.
A Different Conversation at the Bank
Several weeks later, Robert and Margaret returned to the branch for a routine appointment.
They had obtained estimates for their home improvements and wanted to discuss payment options.
Jason recognized them immediately and greeted them warmly.
He explained that Elizabeth had reviewed the branch’s procedures for handling unusual deposits.
Employees now received additional guidance on escalating transactions requiring authorization.
Jason had also completed refresher training on documentation and customer communication.
Robert thanked him for taking the matter seriously.
The couple’s savings remained in their account while they considered the renovation estimates.
They had decided to begin with the entrance steps before addressing the bathroom.
Elizabeth stopped by their desk and asked whether everything was going smoothly.
Margaret smiled and showed her a photograph of the planned entrance.
The fictional story had begun with an elderly couple facing an unexpected refusal.
It ended when a manager distinguished a legitimate review requirement from an unnecessary rejection.
The intervention allowed the deposit to proceed after the appropriate checks were completed.
More importantly, Robert and Margaret left knowing their concerns had been heard and their plans could continue.
After a lifetime of saving for tomorrow, Robert and Margaret finally felt confident that the money they had protected for years could help them live more comfortably today.